
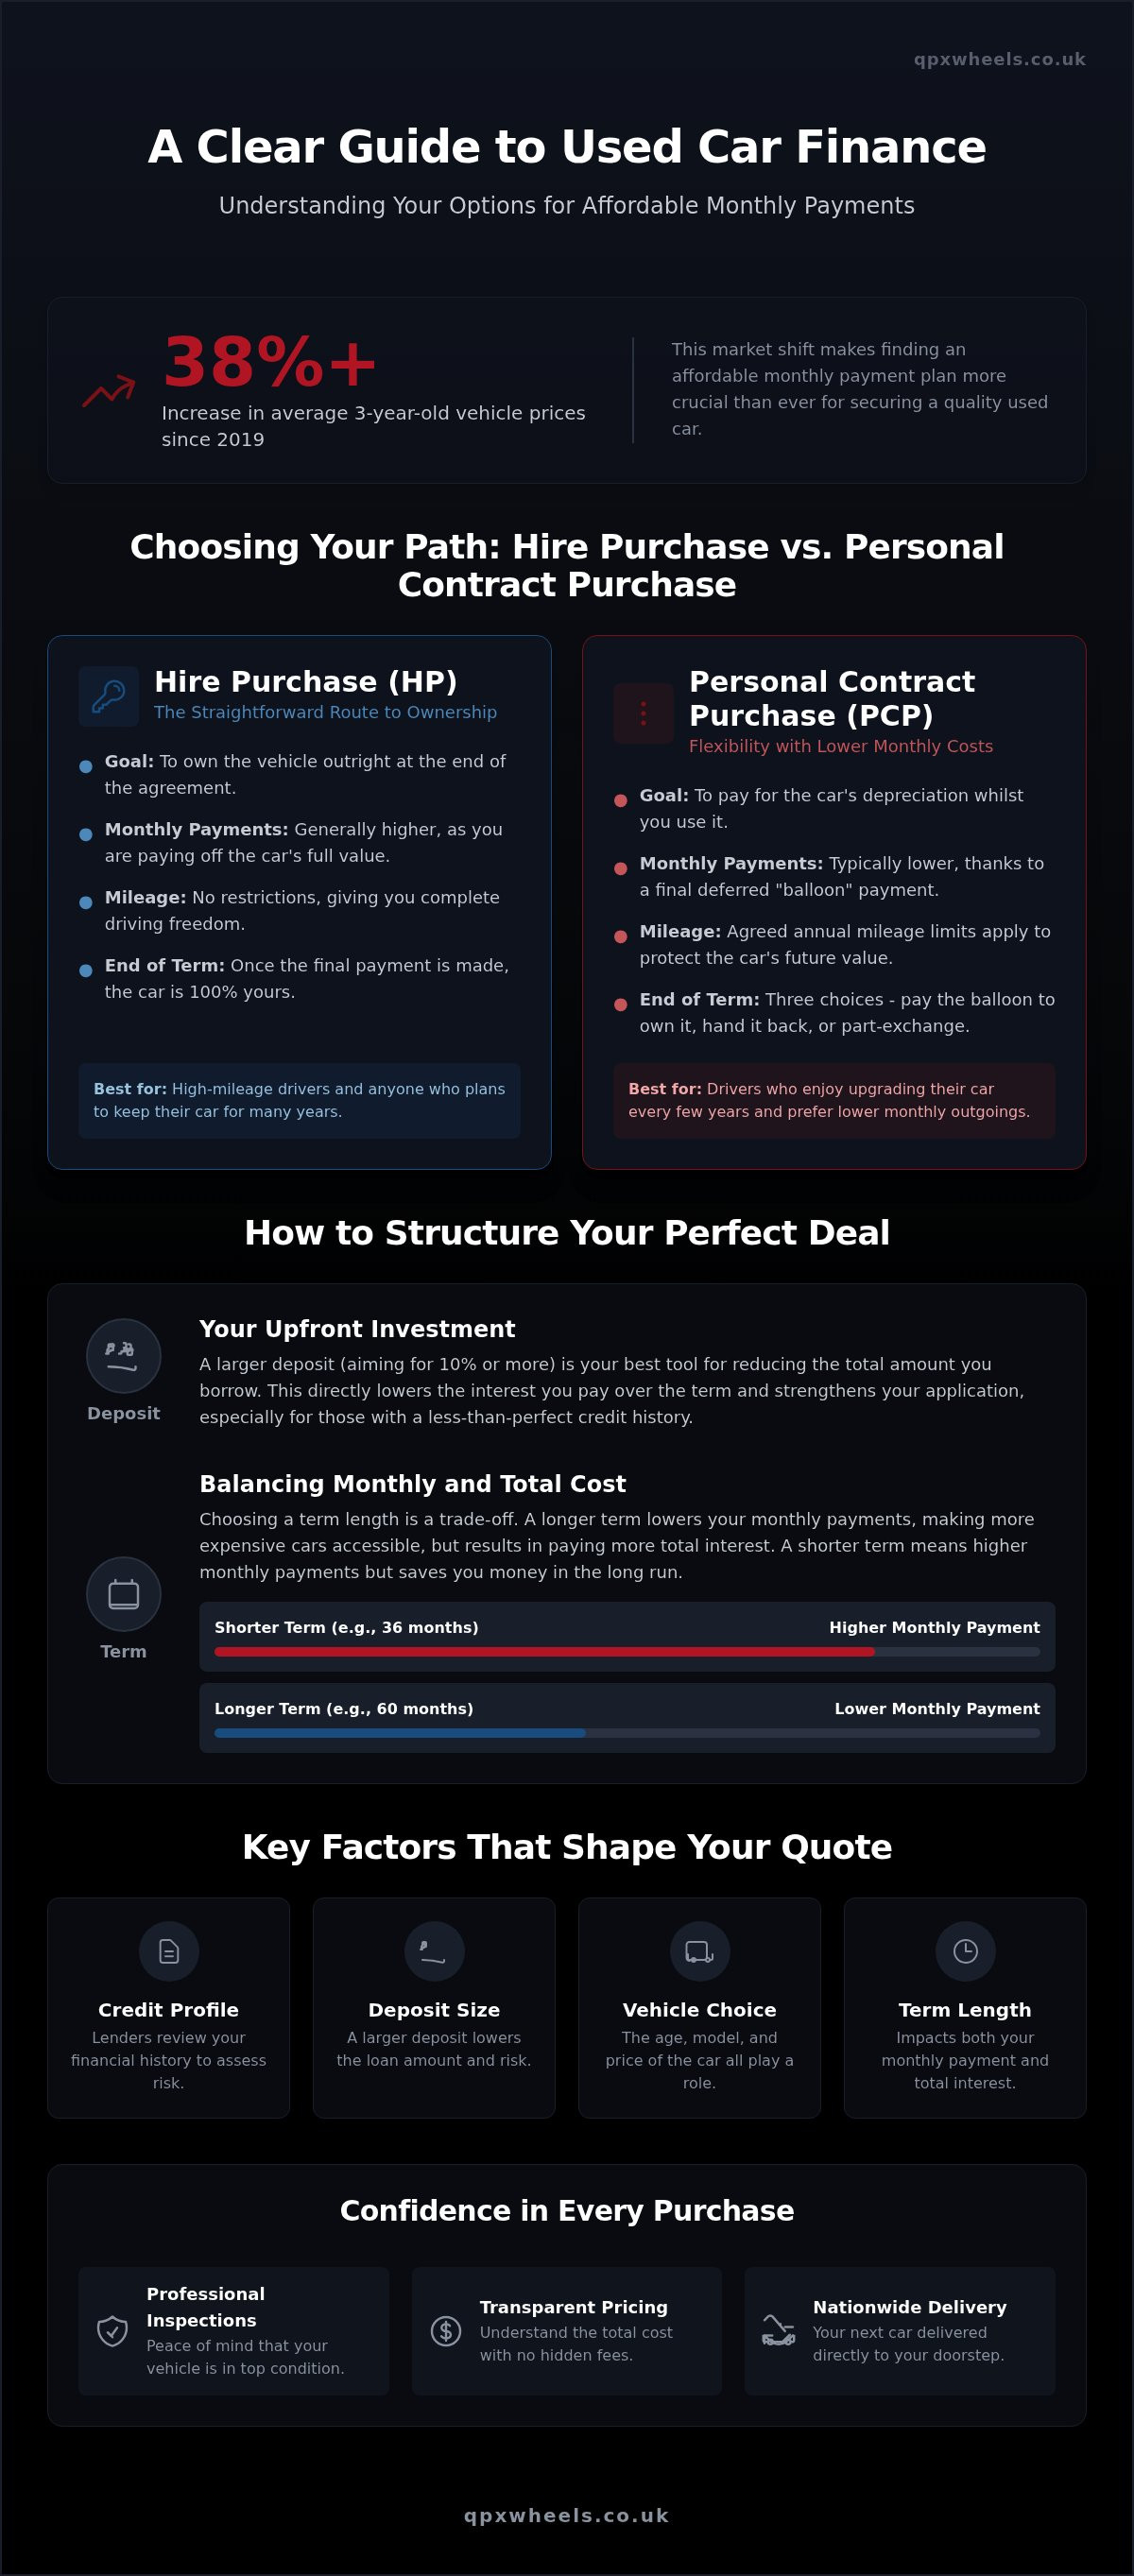
Did you know that the average price of a three-year-old vehicle has surged by more than 38% since 2019? This dramatic shift means that a budget which once secured a nearly new motor now often leads to older models, making the search for affordable monthly payment used cars more vital than ever. It's a challenging market, and it's perfectly natural to feel a sense of hesitation when looking at finance agreements. You might worry about hidden fees lurking in the small print, feel confused by the differences between HP and PCP, or simply feel anxious about whether your credit score will meet the requirements.
We believe that financing your next vehicle should be a source of freedom, not a cause for stress. In this comprehensive guide, you'll discover how to structure a deal that offers total transparency and fits your monthly budget perfectly. We'll demystify the finance process, helping you understand the total cost of ownership whilst ensuring you have complete confidence in the quality of your car. From initial valuation to nationwide delivery at your doorstep, we're here to provide a clear, supportive path to your next purchase, allowing you to focus on the excitement of the journey ahead rather than the complexities of the paperwork.
Key Takeaways
- Learn the fundamental differences between HP and PCP finance to decide whether you prefer long-term ownership or lower monthly outgoings.
- Discover how to structure your agreement by adjusting your initial deposit to lower interest charges and secure affordable monthly payment used cars.
- Identify the key factors lenders use to calculate your quote and how to organise your finances to improve your credit profile before applying.
- Gain peace of mind by understanding the total cost of ownership, ensuring there are no hidden fees or unexpected surprises in your finance agreement.
- Explore the benefits of nationwide delivery and professional vehicle inspections that ensure your next car arrives in top condition directly to your door.
Understanding Monthly Payment Options for Used Vehicles
The way we buy cars in the UK has transformed over the last decade. Rather than saving for years to purchase a vehicle outright, most drivers now prefer to spread the cost over a manageable period. This shift reflects a move away from seeing a car as a static asset to be owned, and more as a monthly service that provides reliable mobility. By focusing on monthly payment used cars, you can often access better specifications or newer models than your upfront savings might otherwise allow.
Choosing the right finance route depends heavily on your lifestyle. Do you drive long distances every year? Do you plan to keep the car for a decade, or do you prefer to upgrade every few years? Answering these questions early helps you decide between the two main paths: Hire Purchase and Personal Contract Purchase. Both offer distinct benefits, but they cater to very different types of drivers.
The Rise of Personal Contract Purchase (PCP)
For many, Personal Contract Purchase (PCP) has become the go-to option. It works by deferring a significant portion of the car's value until the end of the agreement. This "balloon payment" means your monthly outgoings are typically lower because you aren't paying off the full value of the vehicle during the term. Instead, you're essentially paying for the depreciation that occurs whilst you are using it.
At the end of a PCP deal, you have three clear choices:
- Pay the balloon payment to own the car outright.
- Hand the car back and walk away, provided it meets the agreed condition and mileage.
- Trade the car in and use any "equity" as a deposit for your next vehicle.
This flexibility makes PCP ideal for drivers who enjoy changing their car every three or four years and want to keep their monthly budget as lean as possible. It's a proactive way to manage your finances whilst staying in a modern, reliable vehicle.
The Simplicity of Hire Purchase (HP)
If your goal is to eventually own the vehicle without a large final payment, Hire Purchase (HP) is often the more straightforward choice. With HP, the cost of the car is divided equally across your monthly instalments after your initial deposit. Once you've made the final payment, the car is yours. It's a "pay-to-own" structure that offers long-term stability and clarity.
One of the biggest advantages of HP is the lack of mileage restrictions. Since you are paying for the full value of the car, lenders don't usually set limits on how far you can drive. This makes it a fantastic option for high-mileage drivers or those who want the freedom to keep their car for many years after the finance term ends. It's a dependable, logical progression toward full ownership.
How to Structure Your Used Car Finance Deal
Structuring a finance agreement is a balancing act between your current cash flow and your long-term financial health. When searching for monthly payment used cars, the goal isn't just to find the lowest headline figure, but to build a deal that remains sustainable for the life of the loan. By adjusting three key levers: the deposit, the term length, and the part-exchange value, you can tailor an agreement that fits your lifestyle without overextending your bank balance. A well-structured deal provides clarity and ensures you don't face financial pressure halfway through your contract.
Determining Your Ideal Deposit Size
The deposit is your first line of defence against high interest costs. A common rule of thumb is to aim for at least 10% of the vehicle's price, though contributing more is always beneficial. A larger upfront payment reduces the "principal" amount you borrow, which directly lowers the total interest you pay over the term. For buyers with a less-than-perfect credit history, a substantial deposit can often be the deciding factor in securing an approval, as it reduces the lender's risk. If you have an existing vehicle, using our professional vehicle valuation service is a simple way to see how much your current car can contribute towards your next purchase, effectively acting as a cash injection for your deposit.
Choosing the Right Term Length
Your choice of term length has the most immediate impact on your monthly budget. Spreading the cost over 60 months instead of 36 will significantly lower your outgoings, making a premium vehicle more accessible. For example, adding an extra 12 months to a deal can often drop the monthly cost by a noticeable margin, providing extra breathing room in your household budget. However, it's vital to remember that longer terms mean you'll pay interest for a longer period, increasing the total amount you repay over the life of the agreement.
Many financial guides, including authoritative FDIC auto financing tips, suggest that whilst longer loans are tempting, they can lead to "negative equity." This occurs when the car's market value drops faster than the remaining loan balance. This is a particular risk amongst PCP agreements with very long terms, where you might owe more than the car is worth when you want to trade it in. We recommend finding a middle ground that keeps payments comfortable without stretching the loan beyond the car's most reliable years.
Comparing HP and PCP for Your Monthly Budget
When you browse for monthly payment used cars, you'll often see two different prices for the same vehicle. This can be confusing, but it reflects the fundamental difference between Hire Purchase (HP) and Personal Contract Purchase (PCP). HP usually carries a higher monthly cost because you are paying off the entire value of the car. In contrast, PCP offers lower monthly outgoings by deferring a large chunk of the cost until the end. Choosing between them is a debate between your immediate monthly cash flow and the total cost of ownership over several years.
Transparency is vital when comparing these quotes. You should always look at the "Representative APR" (Annual Percentage Rate), which includes both interest and any mandatory fees. Rates vary between dealers based on their lending partners and your credit profile. For those seeking extra guidance on what to look for in a finance agreement, the FTC guide to buying a used car provides excellent foundational advice on dealership finance practices. Both HP and PCP agreements usually allow for early settlement, though the process and potential savings on interest will differ depending on how far into the term you are.
Scenario Analysis: Low vs High Mileage Drivers
Your annual mileage is a deciding factor in which finance model fits your budget. High-mileage drivers often find that HP is the more economical choice in the long run. This is because PCP agreements include strict mileage limits; exceeding these can result in significant "excess mileage" charges when you return the car. Additionally, your predicted mileage directly dictates the size of the PCP balloon payment. Specifically, the more miles you plan to drive, the lower the car's guaranteed future value will be, which subsequently increases your monthly instalments. If you spend a lot of time on the motorway, the "pay-to-own" structure of HP removes these worries entirely.
Ownership vs Flexibility
The choice often comes down to your long-term plans for the vehicle. There is a significant psychological and financial benefit to owning a car outright at the end of an HP deal. Once the final payment is made, your monthly outgoings drop to zero, and you own an asset you can eventually sell or part-exchange. PCP, however, offers the freedom to "hand back the keys" and walk away. This is a great safety net if your lifestyle changes or if the used car market fluctuates unexpectedly. At QPX Wheels, we maintain a diverse inventory, ranging from budget automatics to luxury vehicles, all of which can be tailored to either of these finance paths to suit your individual needs.
Key Factors That Influence Your Monthly Quote
When you look at monthly payment used cars, the figure you see on a screen is often a "representative" example. This means it's the interest rate offered to at least 51% of successful applicants. Your individual quote is shaped by a variety of personal and vehicle-specific factors. Lenders are essentially assessing risk; the more predictable the outcome, the lower the interest rate they are likely to offer. Understanding these variables allows you to prepare your finances effectively before you even step onto a forecourt.
Credit Scores and Finance Approval
Your credit profile is the most significant factor in determining your APR. According to LendingTree data from August 2026, there's a massive gap between credit tiers; those with excellent credit (800+) might see rates around 8.03%, whilst those with poor credit (under 580) can face rates of 24.06% or higher. Before you apply, it's helpful to understand the difference between a "soft" search and a "hard" search. A soft search allows a lender to view your credit report without leaving a mark that other lenders can see. This is a great way to check your eligibility without damaging your score. To improve your chances of a competitive rate, ensure you are on the electoral roll and try to pay down small existing balances. At QPX Wheels, we work with a diverse panel of lenders. This allows us to find tailored solutions that match your specific circumstances.
The Relationship Between Vehicle Age and APR
The car itself plays a major role in the finance calculation. Generally, newer used cars attract lower interest rates than older "budget" models. This is because a newer vehicle is seen as a more reliable asset with a more predictable future value. When balancing your budget, you need to weigh the lower interest rate of a newer car against its faster depreciation. Conversely, an older car might have a higher APR but a much slower drop in market value. It's about finding the sweet spot where the total monthly commitment feels comfortable.
Reliability is another key pillar of lender approval. Every vehicle in our inventory is HPI clear, meaning it has no outstanding finance, hasn't been stolen, and isn't a recorded insurance write-off. This status is vital for securing finance approval and provides you with essential peace of mind. To protect your investment, we offer extended warranties that can be integrated into your agreement, ensuring your monthly budget isn't derailed by unexpected mechanical costs.
Securing Your Next Vehicle with QPX Wheels
Buying a car is a significant commitment that requires a foundation of trust. Choosing an independent specialist with over 16 years of experience provides a level of security that purely online platforms often struggle to match. We act as your seasoned guide, helping you find monthly payment used cars that meet your specific needs without the pressure of aggressive sales tactics. Whether you're looking for luxury vehicles for sale or disabled friendly vehicles, our focus remains on long-term satisfaction and ethical conduct. We believe in building relationships with our customers, moving away from transactional interactions toward a supportive environment.
Nationwide Delivery: From Click to Doorstep
Once your finance is approved, the next step is getting your car home safely and efficiently. We organise nationwide delivery to any UK address, ensuring the process is as smooth as possible for you. Unlike "online-only" competitors, our national reach is backed by nearly two decades of industry expertise and a commitment to high standards. On delivery day, you can expect a professional handover that respects your time. This includes a full inspection of the vehicle whilst you're present, ensuring it meets our high standards before you sign the final paperwork. It's a methodical, stress-free way to engage with your new purchase.
Transparency is the foundation of our business, especially regarding the financial side of the transaction. Our vehicle valuation service is designed to be clear and honest, providing a fair price for your part-exchange. By integrating the value of your current car into your finance agreement, you can significantly reduce your monthly commitment and lower your total interest costs. This structured approach ensures that the most important details of your deal are accessible and easy to understand from the very beginning. We aim to alleviate the typical anxieties associated with hidden fees by providing a logical progression from valuation to final agreement.
The QPX Wheels Difference: Trust and Transparency
We understand the typical anxieties associated with secondary-market purchases. That's why we prioritise a supportive, customer-centric atmosphere that values your peace of mind. Our 16-year reputation in the UK used car market is built on verified quality, from budget automatics to high-end luxury models. Every car is HPI clear and undergoes rigorous checks, so you can drive away with confidence in your vehicle's reliability. We handle the complexities of the transaction so you don't have to worry about the paperwork. Explore our latest used car finance deals and find your next vehicle today.
Taking the Next Step Toward Your Ideal Vehicle
Finding the right car doesn't have to be a source of anxiety. By understanding how to balance your deposit with the right term length, you can secure a deal that stays well within your household budget. Whether you choose the long-term ownership of Hire Purchase or the lower monthly outgoings of PCP, the goal is always clarity and confidence. Structuring monthly payment used cars should be a transparent process that leaves you feeling empowered rather than confused.
At QPX Wheels, we use our 16 years of expertise to act as your dependable guide throughout the entire process. Every vehicle in our diverse inventory is HPI clear, and we offer extended warranty options to protect your investment for the long term. Once your finance is approved, our nationwide delivery service brings your new car directly to your doorstep, anywhere in the UK. We handle the complexities so you can focus on the road ahead. Browse our quality used cars and calculate your monthly payments here and start your journey with a partner you can trust.
Frequently Asked Questions
What is the difference between HP and PCP car finance?
HP (Hire Purchase) spreads the full cost of the car over monthly instalments until you own it. PCP (Personal Contract Purchase) defers a large chunk of the cost to the end, resulting in lower monthly outgoings. Whilst HP is a pay-to-own model, PCP offers more flexibility to change cars every few years. Both are popular routes for structuring monthly payment used cars depending on your long-term ownership goals.
Can I get a used car on finance with a low deposit?
Yes, many lenders offer low-deposit or even zero-deposit finance options, though this depends on your credit profile. Contributing a smaller amount upfront will naturally increase your monthly instalments and the total interest you pay over the term. It's often beneficial to use a part-exchange to boost your deposit size. This helps keep your budget manageable whilst securing a more competitive interest rate from the lender's panel.
Is it better to pay for a used car in cash or on monthly payments?
Paying in cash avoids interest charges, but financing allows you to preserve your savings for emergencies or other investments. Spreading the cost through monthly payment used cars can also enable you to afford a newer, safer, or more reliable vehicle than your current cash savings might permit. The better choice depends on your personal cash flow and whether you prefer liquid assets over outright vehicle equity in the short term.
What happens if I want to end my car finance agreement early?
You can request a settlement figure from your lender at any time to pay off the agreement early. This figure includes the remaining capital and a small amount of interest; it often includes a rebate for the interest you won't be paying. If you've paid at least 50% of the total finance amount, you may also have the right to Voluntary Termination. This allows you to return the car without further payments.
Does the monthly payment include car insurance or maintenance?
Standard HP and PCP agreements typically don't include insurance or routine maintenance costs. You remain responsible for taxing, insuring, and servicing the vehicle according to the manufacturer's schedule. However, we offer extended warranties that can provide protection against unexpected mechanical failures. It's vital to factor these running costs into your monthly budget alongside your finance instalment to ensure total affordability throughout the year. Every detail counts when planning your finances.
How does my credit score affect my monthly car payments?
Your credit score is the primary factor used by lenders to determine the interest rate they offer you. A higher score indicates lower risk, which usually results in a lower interest rate and more affordable instalments. Conversely, a lower score may lead to higher rates or the requirement for a larger deposit. We work with a variety of specialists to find supportive solutions for different credit backgrounds and financial histories.
Can I part-exchange my current car if it still has outstanding finance?
Yes, you can part-exchange a car with outstanding finance by using its value to settle the existing loan. If your car is worth more than the remaining debt, the difference can be used as a deposit for your next vehicle. If it's worth less, the shortfall can sometimes be rolled into your new finance agreement. This will increase your new monthly outgoings, so it's a step that requires careful, professional calculation.
What is a balloon payment in a PCP agreement?
A balloon payment is a large final instalment deferred until the end of a PCP contract. This amount is based on the Guaranteed Future Value of the car, as predicted by the lender at the start of the deal. By not paying this portion during the term, your monthly costs stay lower. At the end, you can pay the balloon to own the car, or simply return the vehicle to the dealer.


