
Did you know that transactions in the used van market are now nearly 12% higher than they were before the pandemic? Whilst new registrations continue to decline, savvy business owners are increasingly turning to the secondary market to keep their operations moving. However, securing used van finance UK can often feel like a minefield of complex VAT rules and fluctuating interest rates. You need a vehicle that works as hard as you do, yet the anxiety of accidentally buying a 'lemon' that breaks down mid-job remains a significant hurdle for many.
We recognise that the fear of high monthly costs or unexpected tax bills is a heavy burden when you're trying to grow your business. It is perfectly normal to feel overwhelmed by the latest 2026 regulations. This guide is designed to provide professional clarity; we will help you master the complexities of finance to secure a cost-effective and dependable vehicle. We will explain how Hire Purchase and PCP options work in the current climate, break down the impact of the £4,170 Van Benefit Charge, and show you how to use extended warranties to ensure long-term peace of mind.
Key Takeaways
- Learn how to secure the best deals for used van finance UK whilst avoiding common pitfalls like the "VAT trap" and high interest rates.
- Understand the differences between Hire Purchase and PCP to decide whether you prioritise long-term vehicle ownership or lower monthly outgoings.
- Discover why many commercial agreements require the 20% VAT as an upfront deposit and how this impacts your business cash flow.
- Master the step-by-step process of sourcing quality commercial vehicles online, from professional valuations to arranging nationwide delivery.
- Leverage over 16 years of industry expertise to ensure your next purchase is backed by extended warranties and a focus on long-term reliability.
Understanding Used Van Finance in the UK
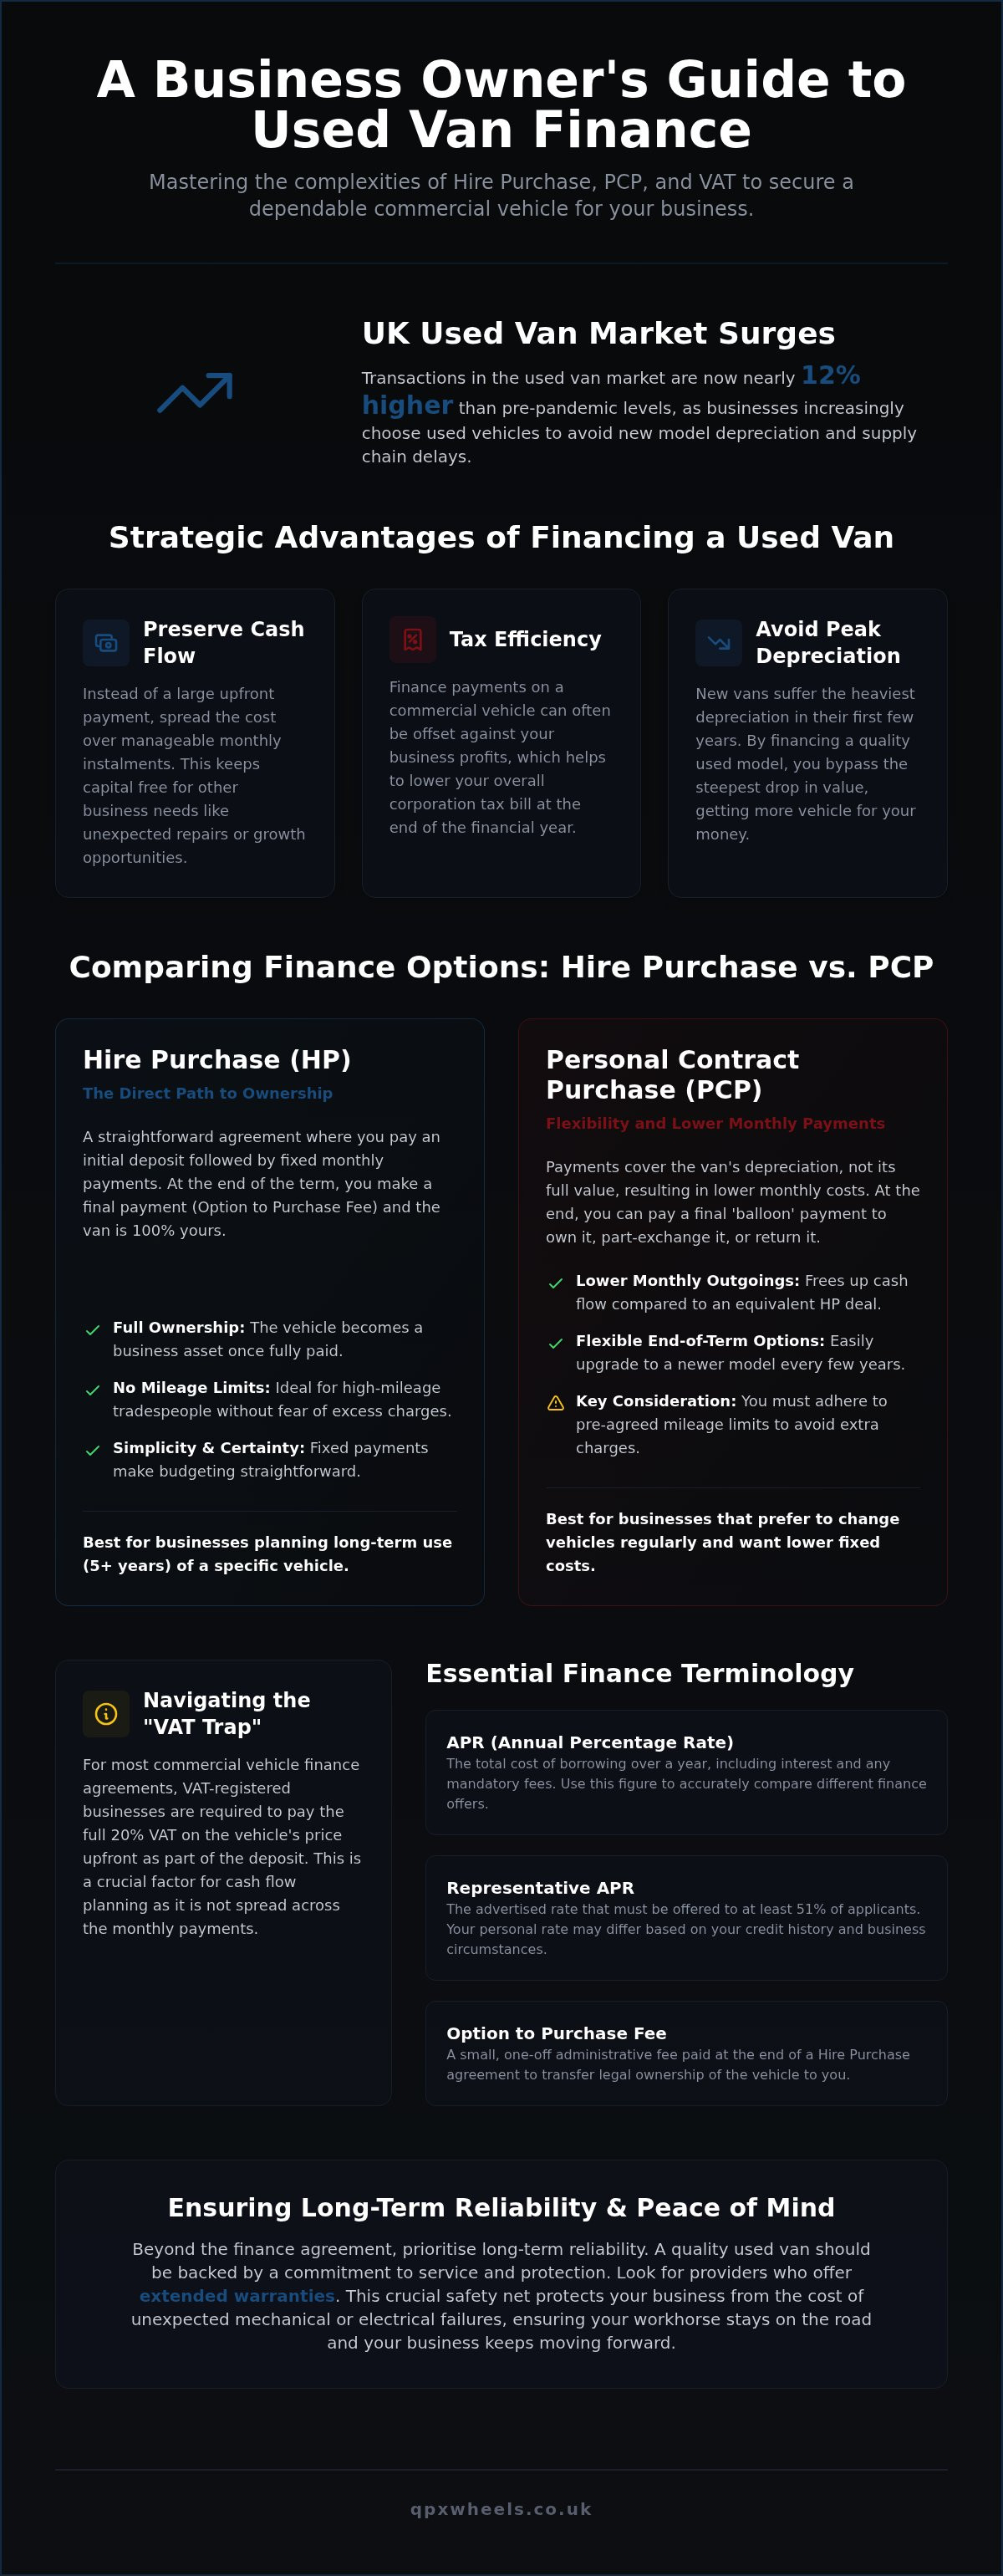
At its core, used van finance UK is a strategic tool that allows you to spread the cost of a commercial vehicle over a manageable period. Rather than paying a large lump sum upfront, you pay in monthly instalments. This approach is particularly effective for tradespeople and small businesses who need to keep their capital working within the company. It differs from car finance because the vehicle is viewed as a revenue-generating asset. Lenders focus on how the vehicle will be used, often requiring you to align your finance plan with your expected annual mileage to ensure the vehicle's value remains stable.
Choosing a used vehicle over a brand new one is a decision rooted in financial logic. New vans suffer from heavy depreciation in their first few years. By opting for a high-quality used model, you avoid that initial value drop whilst still getting a vehicle that meets modern standards. It's a way to get more for your money, perhaps allowing you to afford a higher-specification model or a larger payload capacity. With nationwide delivery options now standard, you aren't limited to what's available in your immediate vicinity, making it easier to find the perfect workhorse.
Why Finance a Used Van Instead of Buying Outright?
Preserving your cash flow is vital for any business, especially when facing the rising costs of 2026. If you spend all your liquid cash on a vehicle, you might struggle to cover unexpected repairs or seize new growth opportunities. Choosing used van finance UK acts as a safety net. It keeps your bank balance healthy whilst providing a reliable van for your daily rounds. Additionally, there are clear tax advantages; finance payments can often be offset against your business profits, which helps to lower your overall tax bill at the end of the year.
Key Terminology Every UK Van Buyer Should Know
To make an informed choice, you need to speak the language of the industry. Understanding Hire Purchase is a great starting point, as it's one of the most common ways to buy a commercial vehicle. Here are three terms you'll encounter:
- APR (Annual Percentage Rate): This figure represents the total cost of borrowing over a year. It includes both interest and any mandatory fees, making it the most reliable way to compare different finance offers.
- Representative APR: This is the rate you'll see in most advertisements. By law, this rate must be offered to at least 51% of people who apply, though your individual rate might differ based on your credit history.
- Option to Purchase Fee: In many agreements, this is a small, one-off payment made at the very end of the term. Once paid, the legal ownership of the van transfers fully to you.
Comparing Hire Purchase (HP) and PCP for Used Vans
Deciding between Hire Purchase (HP) and Personal Contract Purchase (PCP) is a pivotal moment in your search for used van finance UK. These products cater to different business needs, and understanding their mechanics is essential for long-term satisfaction. According to the Finance & Leasing Association, asset finance is a cornerstone of UK business growth, and choosing the right structure depends on your cash flow and how long you intend to keep the vehicle.
Hire Purchase (HP): The Path to Full Ownership
Hire Purchase is remarkably straightforward. You pay an initial deposit, followed by fixed monthly payments over an agreed term. Once the final payment is made, the van is 100% yours. This certainty makes HP the favourite choice for high-mileage tradespeople. Because you are buying the vehicle outright, there are no mileage restrictions or damage charges to worry about at the end of the term. It's the ideal solution for businesses that plan to run a van for five years or more, as it eventually removes the monthly finance cost from your balance sheet entirely.
Personal Contract Purchase (PCP): Flexibility and Lower Payments
PCP offers a different approach by deferring a large portion of the van's value until the end of the agreement. This is known as the 'Optional Final Payment' or balloon payment. Because you aren't paying off the entire cost of the van during the monthly term, your outgoings are significantly lower than with HP. At the end of the contract, you have three choices: pay the balloon to keep the van, part-exchange it for a newer model, or hand it back to the lender.
Flexibility is the main draw here, but it comes with conditions. You must be honest about your predicted mileage from the start. If you exceed the agreed limit, you'll face excess mileage charges when you return the vehicle. It's also worth remembering that PCP is typically reserved for younger used vans. Older vehicles often don't qualify for PCP because their future value is harder for lenders to predict. If you're looking for a newer, low-mileage workhorse with lower monthly costs, you can view our current inventory to see which models qualify for this flexible finance route.
Navigating Credit Scores and VAT on Van Finance
Securing approval for used van finance UK often brings up two main anxieties: your credit score and the upfront VAT. These factors determine not just your monthly payment, but whether you can drive away in your chosen vehicle at all. Independent dealers with a long-standing reputation prioritise transparency here. They ensure you understand every cost before any contracts are signed; this helps alleviate the stress of hidden fees and unexpected hurdles.
VAT and Commercial Vehicle Finance: What You Need to Know
Most commercial vehicles in the UK are subject to 20% VAT. A common hurdle, often called the "VAT trap," occurs because lenders typically require this 20% to be paid in full as a deposit on day one. If a van is listed at £15,000 plus VAT, you'll likely need £3,000 ready to pay immediately. This can be a significant shock to the system if you haven't factored it into your initial budget planning.
It's vital to distinguish between "VAT-qualifying" vans and those sold under the margin scheme. If a van is VAT-qualifying, a VAT-registered business can usually reclaim that 20% deposit in their next return. This is particularly relevant given the current VAT registration threshold of £90,000. For businesses that aren't VAT-registered, the VAT effectively becomes part of the purchase price that cannot be recovered. Understanding this distinction early on prevents cash flow issues later in the process.
Securing Finance with a Less-Than-Perfect Credit History
Your credit profile is the primary factor lenders use to set your interest rate. If you have a high score, you'll likely access the most competitive rates. However, having a limited history or a few missed payments doesn't have to be a dead end. We always recommend starting with a "soft search." This allows a lender to check your eligibility without leaving a mark on your credit file, protecting your score whilst you explore your options.
If your credit is less than perfect, there are several practical steps you can take to improve your chances of approval:
- Increase your deposit: Providing more cash upfront reduces the lender's risk and can sometimes lead to a lower interest rate.
- Consider a guarantor: Having a third party with a strong credit history back your application can provide the security a lender needs.
- Provide proof of income: Showing consistent business turnover or a long-term work contract helps prove your ability to meet monthly payments.
With over 16 years of experience in the industry, we have built relationships with a wide panel of lenders. This expertise allows us to guide you toward the finance provider most likely to approve your specific circumstances, whether you're a seasoned fleet manager or a new start-up. We handle the complexities so you can focus on getting back to work.
The Step-by-Step Process of Financing Your Van Online
The shift toward digital showrooms has fundamentally simplified how you secure used van finance UK. You are no longer restricted to the stock on your local high street; you can now browse a national inventory to find a vehicle that matches your specific trade requirements. Whether you need a specific wheelbase, a high-roof model, or a refrigerated unit, the right workhorse is often just a few clicks away. Once you have shortlisted your ideal van, the digital application process begins. You'll typically need to have your driving licence, proof of address, and recent bank statements ready to upload to a secure portal.
From Online Valuation to Part-Exchange
Most buyers use their current vehicle to fund the deposit for their next purchase. Whilst many websites offer automated 'web' prices, these are often generic and don't account for the specific condition or service history of your van. Using a professional vehicle valuation service ensures you receive a fair and transparent price. This figure is then integrated directly into your used van finance UK agreement, reducing your monthly outgoings. We coordinate the entire transition; your old vehicle is often collected at the same time your new one arrives, ensuring you are never without a van for your work day.
Nationwide Delivery and Finalising Your Agreement
Nationwide delivery is the final piece of the puzzle that makes online financing viable. Reputable dealers mitigate the anxiety of distance-buying by offering delivery to locations such as London and Lancashire. This service bridges the gap between finding the perfect van online and getting it to your place of business. When the vehicle arrives at your doorstep, you have the right to a final inspection before the handover is finalised. This ensures the van matches the description and meets your expectations for quality and reliability.
Distance-buying also comes with specific legal protections that provide peace of mind. Under UK law, you are entitled to a cooling-off period for finance agreements signed away from a dealership's premises. This safety net ensures that you aren't pressured into a long-term commitment without being certain. The entire process is designed to be methodical and secure, allowing you to focus on your daily business operations whilst we handle the complex logistics of the transaction. If you are ready to start your journey, you can browse our current used vans and begin your application online today.
Why QPX Wheels is Your Trusted Partner for Used Van Finance
Finding the right partner for used van finance UK is about more than just numbers on a screen. It's about finding a guide who understands that your van isn't just a vehicle; it's your livelihood. At QPX Wheels, we've spent more than 16 years refining our approach to commercial vehicle sales. We focus on building a foundation of trust, moving away from aggressive sales tactics to prioritise your long-term satisfaction. Our goal is to alleviate the typical anxieties associated with secondary-market purchases by providing professional assurance and approachable warmth.
16 Years of Expertise and National Reach
Since our founding circa 2008, we've grown into a seasoned entity that values its reputation and community standing. Being an independent dealer allows us to offer a level of personalised service that larger corporations often overlook. Every van in our inventory undergoes a rigorous selection process to ensure it is HPI clear, giving you confidence in the vehicle's history and safety. This methodical approach is why thousands of customers from London to Lancashire trust us. Our nationwide delivery service ensures that even if you aren't local, you can still access high-quality commercial vehicles without the stress of a long-distance commute.
Beyond the Sale: Extended Warranties and Peace of Mind
We know that the fear of a breakdown during a busy work week is a major concern. That's why we don't just stop at the sale. We offer comprehensive support through extended warranties that cover essential mechanical components and electrical systems. When you're arranging used van finance UK, adding a warranty provides a safety net that protects your business from unexpected repair bills. It's a proactive way to ensure your van remains on the road where it belongs.
Our role is to be a dependable partner that handles the complexities of the transaction so you don't have to. From professional vehicle valuations for your part-exchange to the final delivery at your doorstep, we guide you through every step. We believe in transparency and ethical conduct, ensuring that every detail of your HP or PCP agreement is clear and easy to understand. This commitment to high standards is what makes us a leader in the UK used vehicle market. We take pride in being the expert voice that simplifies the process, allowing you to focus on growing your business with a reliable vehicle you can trust.
Securing Your Business Future with the Right Van Finance
Navigating the landscape of used van finance UK doesn't have to be a source of stress. By matching your finance structure to your specific business mileage and understanding the upfront VAT requirements, you can secure a reliable workhorse that supports your growth. Whether you choose the long-term ownership of Hire Purchase or the monthly flexibility of PCP, the key is transparency and professional guidance from a partner who understands your trade.
At QPX Wheels, we bring over 16 years of industry experience to every transaction. We specialise in providing HPI clear vehicles backed by extended warranties, ensuring your new asset is as dependable as your own work ethic. Our nationwide delivery service means the perfect van is accessible no matter where your business is based. We handle the complex logistics and paperwork so you can stay focused on the road ahead.
Ready to take the next step toward affordable commercial ownership? Apply for flexible used van finance with QPX Wheels today and let our experts help you find the ideal vehicle for your trade. We look forward to helping you drive your business forward with confidence.
Frequently Asked Questions
Can I get used van finance with no deposit?
Yes, no-deposit finance is possible, but most commercial lenders require the 20% VAT upfront as a deposit. For non-VAT-registered individuals, some lenders offer zero-deposit Hire Purchase agreements subject to credit status. However, paying a deposit usually secures a more competitive interest rate and lower monthly repayments. It's always best to check your eligibility through a soft search first to see which deposit options are available to your business.
Is it better to lease or buy a used van on finance?
Buying a used van through Hire Purchase or PCP is often better if you want eventual ownership and no mileage restrictions. Leasing typically suits those who want a new vehicle every few years without the responsibilities of ownership. With used van finance UK, you benefit from lower depreciation and the ability to keep the vehicle as a long-term business asset once the final payment is made.
How long does the van finance application process take?
Most applications receive an initial decision within minutes, though the full process usually takes between 24 and 48 hours. Once you've provided the necessary documentation and received approval, we can organise the final signatures digitally. Our team works efficiently to ensure your workhorse is ready for nationwide delivery as quickly as possible, minimising any disruption to your daily business operations or client commitments.
What happens if I want to end my finance agreement early?
You can end your agreement early by requesting a settlement figure from the lender. This figure includes the remaining balance and any interest, often with a small rebate for early repayment. Under the Consumer Credit Act, you also have the right to Voluntary Termination if you've paid at least 50% of the total amount payable. We recommend speaking with our seasoned guides to understand the most cost-effective way to settle.
Do I need to be VAT registered to get van finance?
No, you don't need to be VAT registered to secure finance for a commercial vehicle. Both VAT-registered businesses and non-registered individuals or sole traders can apply for Hire Purchase and PCP agreements. If you aren't registered, you simply won't be able to reclaim the 20% VAT often required as a deposit. We help all types of customers navigate these rules to find an affordable and transparent ownership path.
Can I finance a used van if I am a sole trader?
Yes, sole traders are eligible for all major types of used van finance UK. Lenders will typically look at your personal credit score and your business bank statements to assess affordability. Whether you are a plumber, electrician, or delivery driver, we use our 16 years of expertise to find a lender that understands the unique needs of self-employed professionals and provides a supportive and straightforward approval process.
What documents do I need to provide for a van finance check?
You will generally need to provide a full UK driving licence, proof of address from the last three years, and three months of recent bank statements. Some lenders may also request a summary of your business accounts or proof of your current income. Having these digital copies ready to upload to our secure portal will significantly speed up your application and help us secure a decision more quickly for you.
Does used van finance include a warranty?
While the finance agreement itself is a loan for the vehicle, we provide extended warranties to ensure your long-term peace of mind. Every van we sell is HPI clear and undergoes a rigorous inspection process before delivery. A quality warranty covers essential mechanical and electrical components, protecting your business from the anxiety of unexpected repair costs during your daily work rounds and keeping your business moving forward.


