
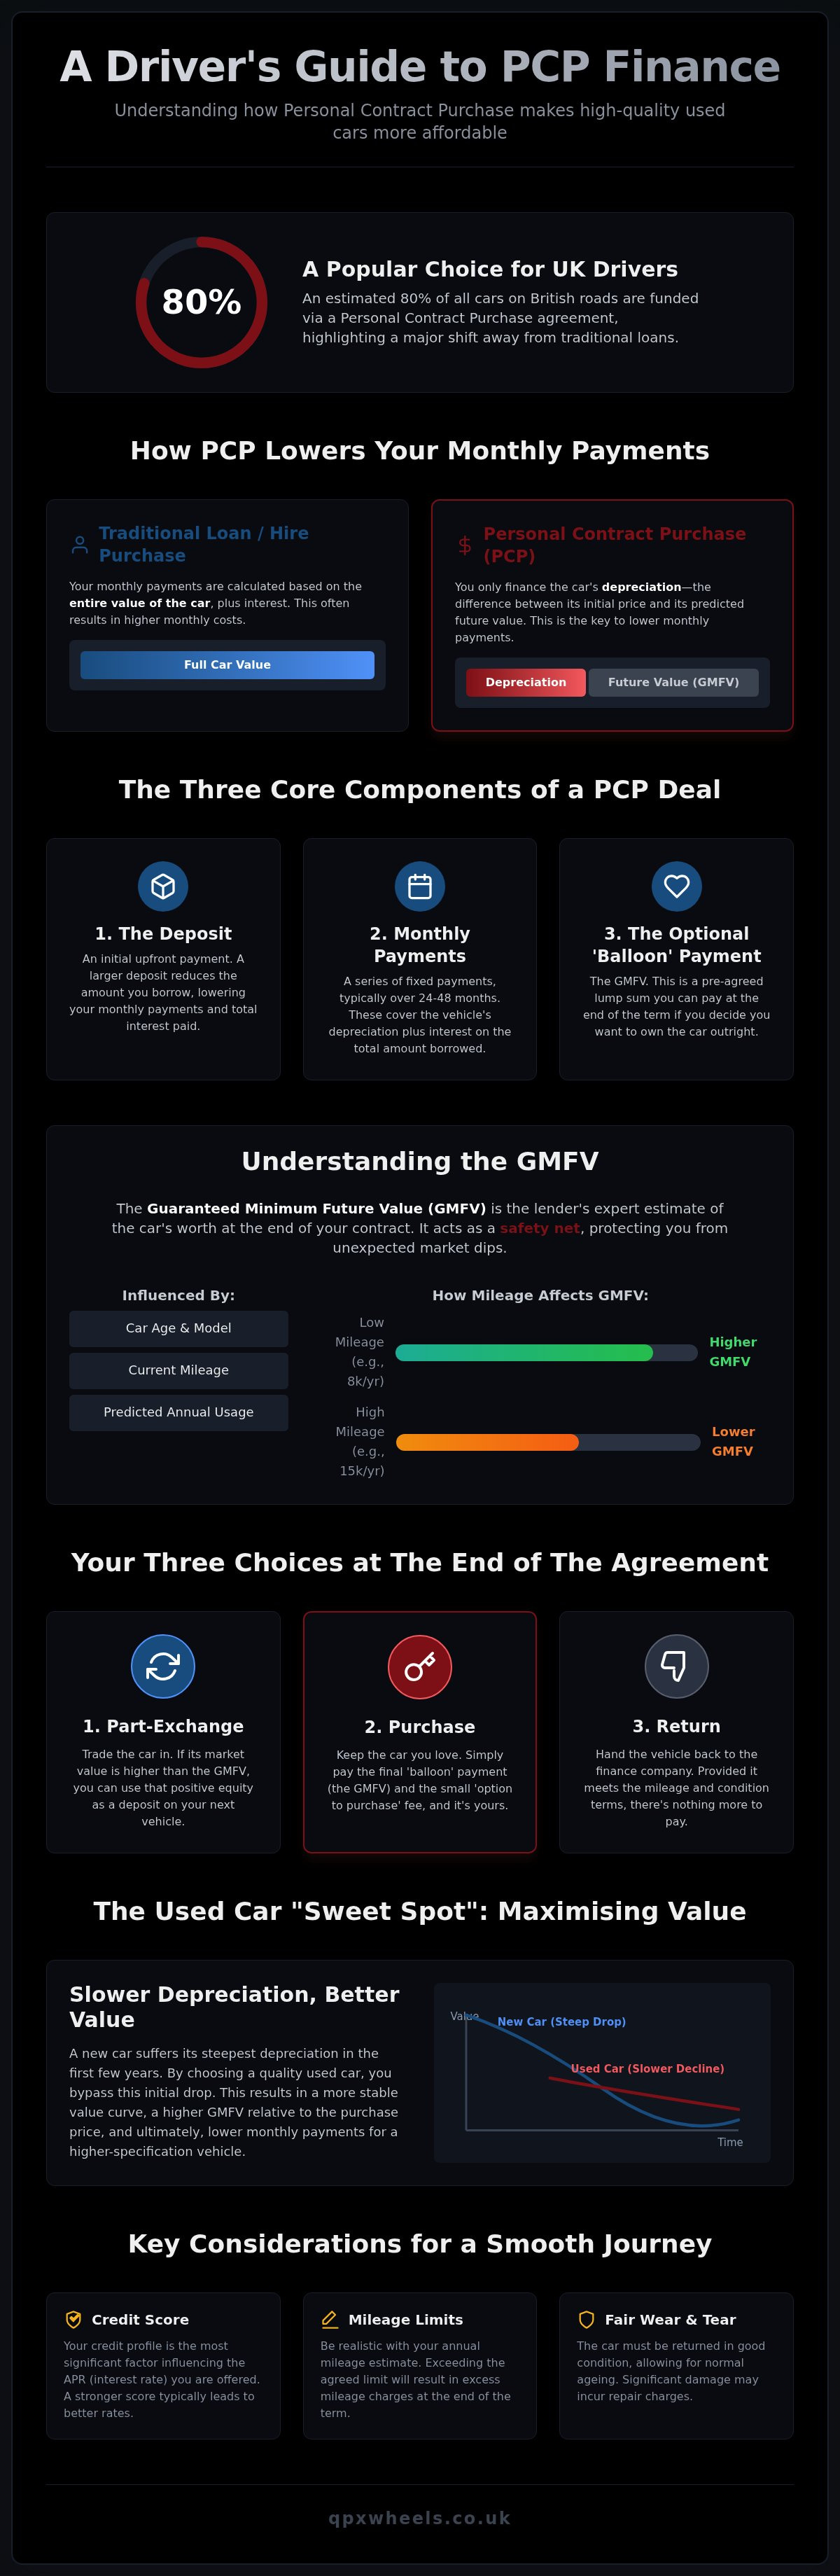
Did you know that approximately 80% of all cars on British roads today are funded through a Personal Contract Purchase agreement? It's a staggering figure that highlights just how many drivers are moving away from traditional bank loans. If you've been searching for PCP finance used cars UK, you likely already know that standard finance options often come with monthly repayments that feel restrictive. It's perfectly natural to feel a bit hesitant about the complexities of balloon payments or the fear of being stuck with an ageing vehicle that has no equity left.
At QPX Wheels, we believe that choosing your next car should be an exciting milestone rather than a source of financial stress. We've put together this guide to show you how PCP makes high-quality, high-spec used cars more affordable through flexible, lower monthly repayments. You'll discover exactly how the Guaranteed Minimum Future Value (GMFV) works to your advantage and how to understand the total cost of ownership with confidence. We'll also cover the latest FCA updates and practical tips for managing mileage limits, ensuring you have all the information needed to drive away with complete peace of mind.
Key Takeaways
- Understand how PCP lowers your monthly commitment by focusing on the car's depreciation rather than its full purchase price.
- Learn the mechanics of the optional "balloon" payment and how it provides the flexibility to either own the vehicle or upgrade to a newer model.
- Compare the benefits of PCP against Hire Purchase (HP) to determine which finance route aligns with your personal budget and ownership goals.
- Discover how to manage your agreement effectively by setting accurate mileage limits and understanding fair wear and tear standards.
- Explore how choosing PCP finance used cars UK allows you to access higher-specification or luxury vehicles for a more manageable monthly cost.
Understanding PCP Finance for Used Cars in the UK
Personal Contract Purchase (PCP) is a flexible finance product specifically tailored for the UK market. It's become the most popular way to drive away in a high-quality vehicle without the heavy burden of large monthly outgoings. Unlike a standard loan where you pay for the entire asset, PCP allows you to pay only for the depreciation of the car during the term. This structure is particularly beneficial for those looking at PCP finance used cars UK, as it makes premium or luxury models much more accessible. By deferring a significant portion of the car's value until the end of the agreement, your monthly cash flow remains healthy whilst you enjoy a newer, more reliable vehicle.
How PCP Differs from a Standard Personal Loan
When you take out a standard personal loan from a high-street bank, you borrow the full purchase price of the vehicle plus interest. You own the car from day one, but your monthly repayments are often high because you're clearing the entire debt at once. In contrast, PCP splits the cost into three distinct parts: a deposit, a series of monthly payments, and an optional final payment. Essentially, PCP is a way to rent the depreciation of a vehicle over a fixed period. This means your monthly payments are typically much lower than a bank loan for the same vehicle, giving you more breathing room in your monthly budget.
The Role of the Guaranteed Minimum Future Value (GMFV)
A central component of Understanding PCP Finance is the Guaranteed Minimum Future Value, or GMFV. This is the lender's expert estimate of what the car will be worth at the end of your contract. This figure is "guaranteed," which acts as a safety net for you. If the used car market suddenly dips, you aren't left out of pocket because the lender has already committed to that value. Experts calculate the GMFV based on the car's age, its current mileage, and your predicted annual usage. For instance, a vehicle covering 8,000 miles a year will typically have a higher GMFV than one covering 15,000 miles. It ensures that at the end of the term, you have the flexibility to hand the car back, part-exchange it, or pay the final sum to keep it forever. This structure protects your equity and keeps your options open as your lifestyle changes.
Calculating Your Monthly Payments and the 'Balloon' Payment
Understanding the maths behind your agreement is the first step to financial confidence. Your monthly repayment isn't just a random number; it's calculated by taking the purchase price of the car and subtracting both your deposit and the Guaranteed Minimum Future Value (GMFV). Essentially, you're paying for the predicted depreciation of the vehicle over the term. It's vital to remember that interest is charged on the entire balance, including the deferred part. For a borrower with a good credit profile, a typical representative APR for a used car deal currently ranges from 8.9% to 10.9%.
The 'Balloon' payment is the optional final sum required if you decide you want to own the vehicle outright at the end of the contract. Understanding Personal Contract Purchase (PCP) involves knowing that this figure is fixed from the start, protecting you from market fluctuations. If you choose to pay it, there is often a small 'option to purchase' fee, typically around £150, to transfer the title into your name. Putting down a larger initial deposit is a smart move here, as it directly reduces the amount you're borrowing and lowers your total interest costs over the 24 to 48 month term.
Why Used Car PCP Offers Exceptional Value
When looking for PCP finance used cars UK, you'll find that used vehicles offer a unique advantage because they've already moved past their steepest period of depreciation. A new car can lose a massive chunk of its value the moment it leaves the forecourt, but a three-year-old car has a much more stable value curve. This stability often leads to a higher GMFV relative to the purchase price, which can result in surprisingly low monthly payments. You might find that you can afford a much higher-specification model amongst our inventory than you would have expected with a standard Hire Purchase agreement.
Factors That Influence Your PCP Quote
Several variables will shape your final quote. Your credit score is perhaps the most significant, as it dictates the APR lenders are willing to offer. Lenders also look closely at your annual mileage estimate. If you set a high limit, the car's predicted future value drops, which increases your monthly payments. It's important to be realistic here; exceeding your limit can lead to excess mileage charges, which typically range between 7p and 10p per mile. If you're unsure about your budget, our vehicle valuation service can help you determine the worth of your current car to use as a part-exchange deposit.
PCP vs Hire Purchase (HP): Which Suits Your Budget?
Deciding between Hire Purchase (HP) and Personal Contract Purchase (PCP) depends largely on your long-term plans for the vehicle. HP is a straightforward path to ownership. You pay for the car's full value over a set period, and once that final payment is made, the car is yours. It's a popular choice for drivers who intend to keep their vehicle for many years. However, if you prefer lower monthly outgoings and the ability to change cars every few years, PCP finance used cars UK often proves more attractive.
Ownership vs Flexibility: The Core Difference
The core difference lies in what happens at the end of your contract. With HP, ownership is the goal. With PCP, the goal is choice. You have three distinct options: pay the balloon sum to keep the car, hand it back to the lender, or part-exchange it for a newer model. This 'return' option is a significant advantage for used car buyers. If a car's maintenance needs increase as it ages, or if you're concerned about its future reliability, you can simply return it without further obligation, provided it meets the agreed condition.
Drivers often find that part-exchanging is the most rewarding route. If the car is worth more than the Guaranteed Minimum Future Value (GMFV) at the end of the term, you have "equity". This surplus can be used as a deposit for your next car, effectively lowering your next set of monthly payments. This cycle allows you to drive a better vehicle than you might otherwise afford through a standard bank loan.
Is PCP Better for Newer Used Cars?
Selecting the right finance product often depends on the vehicle's age. PCP is typically most effective for used cars under five years old. Lenders are more likely to offer competitive terms on these vehicles because they still hold significant resale value. For older, high-mileage vehicles, HP may sometimes be the more viable route. This is because the depreciation on an older car is less predictable, making it harder for lenders to set a high GMFV. Whilst HP doesn't come with mileage restrictions, PCP requires you to be honest about your driving habits to avoid extra costs.
Lenders typically prefer cars that will still have a strong market presence at the end of the term. At QPX Wheels, we specialise in helping you find the right balance. Whether you're looking at budget automatics or luxury vehicles, we'll help you find a deal that respects your budget and your future plans.
Managing Your Agreement: Mileage and Condition
Setting a realistic annual mileage limit is one of the most important steps when arranging PCP finance used cars UK. This figure is used to calculate the car's future value, so being accurate helps you avoid unexpected costs. If you decide to return the vehicle at the end of the term, any miles over the agreed limit will attract a "pence-per-mile" charge. In the current UK market, these charges typically sit between 7p and 10p per mile, though they can reach 30p for certain high-performance models. It's always better to choose a limit that reflects your actual driving habits, including those occasional long-distance trips, to keep your options open.
Understanding Fair Wear and Tear Standards
You don't need to return the car in showroom condition, but you must look after it. Lenders follow the BVRLA (British Vehicle Rental and Leasing Association) "Fair Wear and Tear" guidelines to distinguish between normal usage and genuine damage. This industry standard ensures that you aren't unfairly charged for the typical effects of time and road use. To protect your investment, ensure the car is serviced according to the manufacturer's schedule and keep all your receipts.
- Small stone chips and minor surface scratches are generally acceptable under these rules.
- Large dents, holes in the upholstery, or heavily kerbed alloys usually require repair before return.
- Missing spare keys or incomplete service records can significantly impact the final valuation.
If you are browsing our selection of vehicles at QPX Wheels, keeping your vehicle in top shape ensures the GMFV remains protected. This gives you the best chance of having equity to put toward your next car when the agreement ends.
What Happens if Your Circumstances Change?
One of the biggest fears for buyers is being "locked in" if their situation changes. Thankfully, UK law provides a safety net called Voluntary Termination. Once you've paid 50% of the total amount payable, which includes the balloon payment and all interest, you have the legal right to return the car and end the agreement. This is a powerful consumer right that provides peace of mind if your budget suddenly tightens or your needs change unexpectedly.
You also have the flexibility to settle the agreement early. By requesting a payoff figure from the lender, you can see exactly what's owed to end the contract. If your used car is worth more than this settlement figure, you can sell it or part-exchange it immediately. This often happens when used car prices remain high, allowing you to move into a newer model sooner than you originally planned without waiting for the full term to expire.
Securing Your Used Car Finance with QPX Wheels
Choosing the right vehicle is only half the journey. Finding a finance partner who understands your needs is just as critical. At QPX Wheels, we act as a professional finance broker to ensure you secure a deal that aligns with your specific financial profile. Whether you're looking for budget automatics or high-spec luxury vehicles, our entire inventory is eligible for PCP finance used cars UK. We understand that every driver has different needs, which is why we offer a tailored approach to every application we handle.
To make your transition even easier, we provide a professional vehicle valuation service. This allows you to understand exactly what your current car is worth so it can serve as a solid deposit for your next PCP agreement. Once the deal is finalised, our nationwide delivery service ensures that your chosen car reaches your doorstep anywhere in the UK. This means you can access our premium stock and competitive finance rates regardless of where you're located. We've spent over 16 years refining this process to make it as straightforward as possible for our customers.
Our Transparent Approach to Finance
We prioritise clarity above all else. Our team takes the time to explain the mechanics of the balloon payment, ensuring you feel confident about your choices at the end of the term. We handle all the complex paperwork on your behalf, making the process of switching cars entirely seamless. Because we value long-term satisfaction and reliability, we also offer extended warranties. This extra layer of protection safeguards you against unforeseen mechanical issues, allowing you to enjoy your new vehicle with total peace of mind and confidence in your purchase.
How to Get Started with Your Application
Taking the next step is straightforward. You can browse our diverse range of quality used cars and vans online from the comfort of your home. Our digital tools allow you to get a preliminary valuation of your current vehicle, which helps you plan your budget more effectively. Once you've found a car that catches your eye, contact our friendly team to discuss a tailored PCP quote. We'll work with you to find a monthly payment that fits your lifestyle perfectly without any high-pressure sales tactics. View our latest used car stock and finance options to begin your journey toward a more affordable way of driving today.
Finding the Right Path to Your Next Vehicle
Choosing PCP finance used cars UK is about more than just lowering your monthly outgoings; it is about gaining the flexibility to drive a high-quality vehicle that fits your current lifestyle. By understanding how the balloon payment and mileage limits work, you can manage your agreement with complete confidence. Whether you value the ability to upgrade every few years or simply want a more manageable way to access luxury models, PCP provides a structured and transparent route to the driver's seat.
At QPX Wheels, we bring over 16 years of expertise in the UK used vehicle market to help you find the perfect deal. Our role as a transparent finance broker means we handle the complexities for you, offering highly rated customer service that prioritises your long-term satisfaction. With nationwide delivery available for all financed vehicles, your ideal car is never out of reach. Explore our latest used car deals and PCP finance options today. We look forward to helping you start your next journey on the road with total peace of mind and the right financial support behind you.
Frequently Asked Questions
Can I get PCP finance on a used car older than 5 years?
Yes, you can often secure PCP finance on older cars, although lenders typically require the vehicle to be under a certain age, often ten years, by the end of the agreement. This means a five-year-old car on a four-year term is usually acceptable. For much older vehicles, Hire Purchase might be a more common alternative as depreciation becomes harder for lenders to predict accurately for the final payment.
What happens if I go over my mileage limit on a PCP deal?
Exceeding your mileage limit results in a "pence-per-mile" charge, but only if you choose to return the vehicle at the end of the term. These charges typically range from 7p to 10p per mile in the UK. If you decide to pay the balloon payment or part-exchange the car, these specific excess charges usually don't apply, though high mileage will naturally affect the car's trade-in value when you swap.
Do I have to pay the balloon payment at the end of the term?
No, the balloon payment is entirely optional. You only pay this final sum if you wish to take full ownership of the vehicle. If you'd rather move into a newer model, you can part-exchange the car or simply hand it back to the lender. This flexibility is a core reason why PCP finance used cars UK remains such a popular choice for budget-conscious drivers who enjoy changing vehicles regularly.
Is PCP cheaper than Hire Purchase for used cars?
Monthly repayments on a PCP deal are almost always lower than Hire Purchase because you aren't paying off the car's full value. However, because interest is calculated on the total amount borrowed, including the deferred balloon, the total cost of credit over the whole term might be higher. It's a trade-off between lower monthly outgoings and the eventual total cost of ownership if you keep the car.
Can I part-exchange my current car as a deposit for PCP?
Yes, part-exchanging your current vehicle is a very common way to cover the initial deposit. At QPX Wheels, we provide a professional valuation service to help you understand your car's current market worth. Using this equity can significantly reduce your monthly repayments and make higher-specification used cars more affordable within your monthly budget, often allowing you to access a more premium model than expected.
What is a GMFV and why does it matter for my used car?
GMFV stands for Guaranteed Minimum Future Value, and it represents the lender's expert prediction of what your car will be worth when your contract ends. This figure is vital because it protects you from unexpected drops in the used car market. If the car's actual market value falls below this guarantee, you can still hand it back without being out of pocket for the difference in value.
What happens if the car is worth less than the balloon payment at the end?
If your car's market value drops below the balloon payment, you are protected by the GMFV. You can simply return the car to the lender and walk away with nothing more to pay, provided you've met the mileage and condition requirements. This effectively shifts the risk of negative equity from you to the finance company, providing significant financial security when choosing PCP finance used cars UK.
Can I end my PCP agreement early if I want to change cars?
You can end your agreement early by requesting a settlement figure from your lender at any time. If the car is worth more than the remaining balance, you can part-exchange it for a newer model immediately. Additionally, under UK law, you have the right to Voluntary Termination once you've paid 50% of the total amount payable, allowing you to return the car and end the contract legally.


