
Did you know that the average cost of a funded pre-owned vehicle in the UK has climbed to £11,018 in 2026? This means that securing the right deal on used cars with finance is now a vital part of your car-buying journey. It's entirely natural to feel some anxiety about the process; perhaps you're worried about credit rejections or you're feeling overwhelmed by the difference between a representative APR and what you'll actually pay. You want transparency and a clear path to a reliable vehicle, but the fear of hidden fees can often stand in the way of your excitement.
We've spent 16 years acting as a dependable guide for drivers across the country, and we're here to simplify these complexities for you. This guide provides a clear, step-by-step masterclass on understanding Hire Purchase (HP) and Personal Contract Purchase (PCP) in today's market. We'll explain why a 10.9% APR is considered competitive right now and how to budget for the total cost of ownership. From explaining credit approvals to ensuring a smooth delivery of your next car, we've organised everything you need to know to move forward with total confidence.
Key Takeaways
- Understand why financing is a strategic way to preserve your cash flow whilst driving a reliable pre-owned vehicle.
- Compare Hire Purchase and Personal Contract Purchase to decide whether full ownership or lower monthly costs suit your budget.
- Learn how to organise your credit profile and use soft searches to protect your rating before starting the application process.
- Follow our expert guide to purchasing used cars with finance to ensure every cost is transparent and every step is stress-free.
- Gain the confidence to select the right vehicle from a diverse range, from budget-friendly automatics to specialist vans.
Understanding Used Car Finance: Why It Is the Favourite Choice for UK Buyers
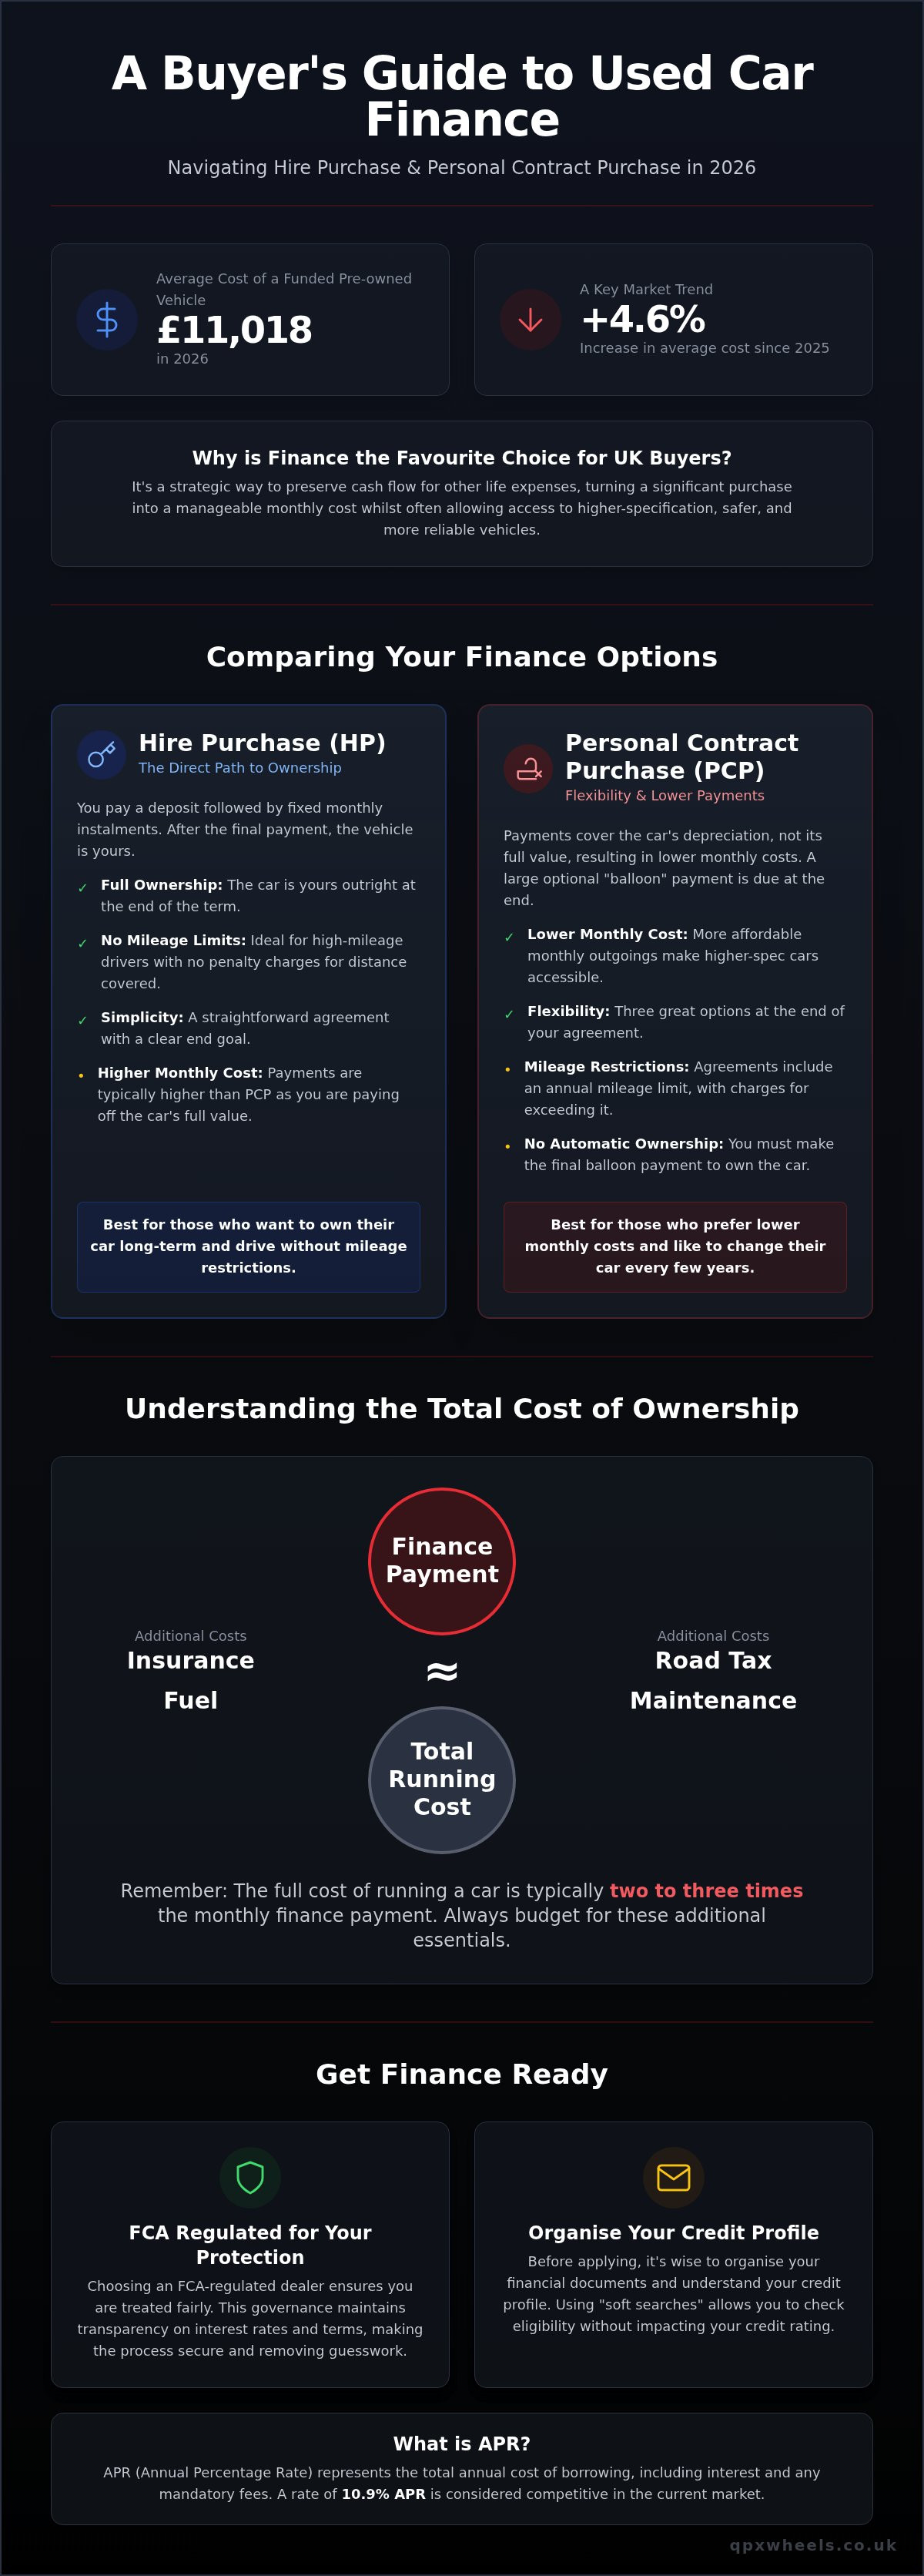
Used car finance is a practical method to acquire a vehicle by paying monthly instalments whilst the lender holds a secured interest in the car. For many drivers, it's the preferred way to buy because it preserves essential cash flow. Instead of a single lump sum exit from your bank account, you can keep your savings for other life expenses or emergencies. This approach turns a significant purchase into a manageable monthly cost, providing a sense of financial stability that outright buying often lacks.
In 2026, market trends show a clear shift toward this model. With the average cost of a funded used car rising by 4.6% since 2025, many buyers find that used cars with finance offer a more sustainable way to access reliable transport. It isn't just about getting from A to B; it's about getting there in a vehicle that offers better safety features and newer technology. Financing often allows you to look at higher-spec models or even luxury vehicles that would be out of reach if you were paying cash upfront. By spreading the cost, you can drive a car that better suits your lifestyle and long-term needs.
The Role of the Financial Conduct Authority (FCA)
The FCA regulates the motor finance industry to ensure you're treated fairly throughout your journey. Their oversight is vital for maintaining transparency, especially regarding how interest rates and commissions are handled. When you choose an FCA-regulated dealer like QPX Wheels, you're working with a partner committed to ethical standards and clear communication. This regulation is particularly relevant if you're considering a Personal Contract Purchase (PCP), as it ensures all terms are presented clearly before you sign. It removes the guesswork and helps alleviate the typical anxieties associated with secondary-market purchases, making the process of buying used cars with finance far more secure.
Total Cost of Ownership vs. Monthly Payments
It's easy to focus solely on the "sticker price" of a car, but monthly affordability is what truly matters for your day-to-day life. When calculating your budget, factor in more than just the finance payment. In 2026, the full cost of running a car, including insurance, fuel, tax, and maintenance, is typically two to three times the monthly finance payment. This is why a methodical approach to your budget is so important. APR is the annual cost of borrowing including interest and mandatory fees. By looking at the APR rather than just the interest rate, you get a much clearer picture of the total cost. This transparency ensures there are no hidden surprises, allowing you to enjoy your vehicle with complete peace of mind.
Comparing Your Options: Hire Purchase (HP) vs. Personal Contract Purchase (PCP)
Choosing the right path for used cars with finance often feels like a fork in the road. On one side, you have Hire Purchase (HP), which is a clear, methodical route to full ownership. On the other, Personal Contract Purchase (PCP) offers lower monthly costs and greater flexibility. Your decision usually hinges on how many miles you cover and whether you intend to keep the vehicle for the long haul or upgrade every few years. Most UK buyers in 2026 now opt for a 48-month term, but the structure of those payments varies significantly between these two popular products.
Hire Purchase (HP) Explained
HP is a straightforward path to ownership that functions much like a traditional secured loan. You start by paying a deposit, followed by fixed monthly instalments that cover the remaining value of the car plus interest. Typical APR rates for HP in 2026 range from 8% to 18% depending on your credit profile. The primary benefit of this arrangement is certainty. Once you've made the final payment, the car is yours entirely, and there is no large "balloon" payment to worry about at the end of the term.
This option is the superior choice if you are a high-mileage driver. Unlike other finance products, HP agreements don't come with annual mileage restrictions. If you drive 20,000 miles a year for work or family trips, you won't face any penalty charges when the agreement ends. Whilst the monthly costs are higher than PCP because you're paying off the full value of the vehicle, the long-term cost is often lower because you avoid the interest that accumulates on a deferred final payment.
Personal Contract Purchase (PCP) Explained
PCP is designed for flexibility and lower immediate outgoings. It works by deferring a large chunk of the car's value until the end of the agreement. This deferred amount is known as the balloon payment, and it's calculated based on the Guaranteed Minimum Future Value (GMFV). This figure acts as a safety net; it's the lender's promise of what the car will be worth at the end of the term, which protects you if used car prices suddenly drop. Rates for PCP are currently between 7% and 15% for buyers with strong credit scores.
At the end of a PCP contract, you have three clear choices. You can pay the balloon payment to own the car, hand the keys back and walk away, or part-exchange the vehicle for a newer model. However, you must stay within an agreed mileage limit. In 2026, excess mileage charges typically range from 3p to 30p per mile, so it's vital to be accurate about your driving habits when setting up the deal. For more impartial advice on these protections, you can consult the Citizens Advice guide to buying a used car. If you prefer lower monthly outgoings and like the idea of driving a newer vehicle every few years, you can explore our PCP finance options to see how they fit your lifestyle.
When assessing your long-term goals, consider how long you plan to keep the vehicle. If you want a reliable car to drive for the next decade, HP provides the most direct route to that goal. If you're someone who values having the latest technology and lower monthly commitments, PCP offers a flexible alternative that keeps your options open. Securing used cars with finance doesn't have to be confusing as long as you match the product to your specific driving needs and future plans.
How to Organise Your Credit and Budget Before Applying
Before you step onto a forecourt, you should have a clear view of your financial standing. Checking your credit report with agencies like Experian or Equifax is a vital first step in the journey of buying used cars with finance. It allows you to see exactly what a lender sees. You'll need to distinguish between "soft" searches, which don't affect your score, and "hard" searches that occur during a formal application. Too many hard searches in a short period can lower your rating, so it's best to check your eligibility through soft searches first to protect your profile.
Many buyers worry that a less-than-perfect history will lead to an immediate rejection. This isn't always the case. Specialist dealers often work with a panel of lenders who look beyond a single number to understand your current affordability. Whilst a lower score might mean a higher interest rate, it doesn't necessarily close the door on a reliable vehicle. Being honest about your history allows a seasoned guide to find the product that best fits your circumstances.
Quick Wins to Boost Your Credit Score
Small adjustments can make a big difference to your approval odds. Start by ensuring you're on the electoral roll at your current address; lenders use this to verify your identity quickly. If you spot any errors on your file, such as an incorrect address or a settled debt marked as outstanding, get them corrected immediately. Additionally, saving for a larger deposit is one of the most effective ways to reduce a lender's risk. A bigger upfront payment often unlocks lower APRs and makes your application more attractive to a wider range of finance providers.
Calculating Your True Monthly Budget
Setting a budget requires a realistic look at your take-home pay. Financial experts often suggest that your total car-related outgoings should not exceed 20% of your monthly income. With the Bank of England base rate held at 3.75% in March 2026, it's wise to leave a small buffer for other rising costs. Don't forget to account for initial expenses like insurance premiums and the V5C logbook transfer. A part-exchange can act as your deposit to lower monthly costs, making a higher-spec vehicle much more affordable without increasing your monthly commitment. By preparing your budget with this level of detail, you can shop for used cars with finance with total peace of mind.
Step-by-Step: How to Buy Your Next Vehicle with Finance
Once you've organised your credit and budget, the actual purchase process should be a smooth, methodical sequence. Securing used cars with finance is no longer just about visiting a local showroom; it's a digital-first experience that puts you in control of every detail. By following a structured approach, you can move from browsing to driving with total professional assurance.
First, you'll choose your vehicle from a diverse inventory. Whether you're looking for specialist vans, budget-friendly automatics, or luxury SUVs, ensure the vehicle is HPI-clear to avoid any hidden history. Next, use an online finance calculator. This tool is essential for finding a monthly payment that fits within that 20% rule we discussed earlier. It allows you to adjust your deposit and term length in real time to see exactly how it impacts your outgoings.
The third step is submitting your application. This is where you provide your documentation to prove affordability. Once approved, you'll reach the most important stage: reviewing the finance agreement. Always pay attention to the "Right to Withdraw" clause. This gives you a 14-day window to cancel the finance agreement if you change your mind, though you'd still need to find an alternative way to pay for the vehicle. Finally, you can arrange for delivery or collection of your new car.
Documentation You Will Need
To keep the process efficient, have your paperwork ready before you start your application. Lenders require specific verification to finalise the deal and protect both parties:
- A valid UK driving licence (ensure it reflects your current home address).
- Proof of address, such as utility bills or bank statements from the last three months.
- Recent payslips or bank statements to demonstrate a steady income to the lender.
The "Click to Doorstep" Experience
For many buyers, the most convenient option is Nationwide Car Delivery. This service ensures that your vehicle arrives at your home or workplace without you needing to travel across the country. The paperwork is typically signed digitally or upon arrival, ensuring every detail is in order before the car leaves the centre. This approach respects your time and simplifies the logistics of a secondary-market purchase.
When the vehicle arrives, take your time with a physical inspection and a short test drive. Even with our 16-year reputation for quality, we encourage every customer to verify that the car meets their expectations. If you're ready to find your next vehicle, you can browse our current stock and apply for finance online today.
Why Choose QPX Wheels for Your Financed Used Car or Van
With over 16 years of industry experience, QPX Wheels has grown into a trusted partner for drivers seeking quality used cars with finance. We understand that every buyer has a unique set of requirements, which is why our inventory is intentionally diverse. Our stock ranges from high-specification luxury SUVs to reliable, budget-friendly automatics, ensuring that whether you're a first-time driver or a seasoned professional, you'll find a vehicle that fits your life. This breadth of choice is backed by our commitment to reliability, moving away from aggressive sales tactics toward a supportive, customer-centric atmosphere.
Our service doesn't end at the showroom doors. We offer a seamless nationwide delivery service that brings your chosen vehicle directly to your home or workplace. This practical approach respects your time and ensures that even if you're buying from the other side of the country, you receive the same level of care and professional assurance as a local customer. We take pride in being a dependable guide, handling the complexities of the transaction so you don't have to.
A Reassuring Approach to Finance
Our philosophy is built on transparency and long-term satisfaction. We see ourselves as your partner in the finance process, prioritising clear communication at every stage. Because we work with a broad panel of lenders, we can explore various options to find the most competitive rates for your specific credit profile. This is particularly helpful if you've been worried about credit rejection or hidden fees in the past. To further alleviate any anxiety, we offer extended warranties on our vehicles, providing a safety net that ensures your ownership experience remains positive. When you choose used cars with finance from us, you're gaining a support system dedicated to your peace of mind.
Specialist Vehicles: Vans and Mobility Cars
We take particular pride in our specialist stock, which includes a wide selection of used vans and disabled-friendly vehicles. For business owners, financing a van is often a strategic move for tax efficiency, allowing you to manage cash flow whilst growing your trade. Our team understands the specific needs of commercial buyers and can help you select the right finance product to suit your business cycle. We focus on the practical details, ensuring you have a reliable tool for your work without the stress of a lump sum payment.
Equally important is our expertise in mobility solutions. We specialise in disabled-friendly transport, providing vehicles that offer necessary accessibility without compromising on quality or style. We know that organising finance for mobility cars can feel complex, so we handle the details for you. From the initial vehicle valuation to the final delivery, we ensure the process is steady and methodical. This commitment to inclusivity and ethical conduct is what defines our reputation in the local community and across the UK.
Browse our current stock and explore finance options today.
Secure Your Next Vehicle with Confidence
Securing used cars with finance doesn't have to be a source of stress. By distinguishing between Hire Purchase and Personal Contract Purchase, you can choose a payment structure that aligns with your annual mileage and long-term ownership goals. Remember that organising your credit file and setting a realistic budget are the most effective ways to ensure a smooth approval. When you approach the market with these tools, the process becomes a clear path to a reliable vehicle rather than a confusing maze of numbers.
At QPX Wheels, we've spent 16 years acting as a seasoned guide for drivers across the UK. As an FCA Regulated Dealer, we prioritise transparency and ethical conduct in every agreement. Whether you need a budget automatic or a specialist van, our team is here to handle the complexities for you. We even offer nationwide delivery to bring your new car straight to your doorstep. You deserve a transaction that feels honest and grounded. We look forward to helping you get behind the wheel of a car you'll love for years to come.
Explore our latest used cars and vans with competitive finance deals
Frequently Asked Questions
Can I get a used car on finance with a poor credit score?
Yes, it's often possible to secure used cars with finance even if your credit history isn't perfect. Many lenders in 2026 focus on your current affordability and employment stability rather than just a historical score. Working with an experienced dealer who has access to a wide panel of specialist lenders can significantly improve your chances of approval by finding a product tailored to your specific circumstances.
What is the minimum deposit required for used car finance?
Many lenders offer "no deposit" options, meaning you can start your agreement with £0 upfront. However, providing a deposit of at least 10% is usually recommended as it reduces the total amount you borrow and can often lead to a more competitive APR. A larger deposit also lowers your monthly instalments, making the vehicle more affordable over the entire term of the agreement.
How long does the car finance approval process take?
The initial approval process is often very quick, frequently taking just a few minutes to a few hours. Whilst automated systems handle the majority of checks, some applications may require a manual review that takes 24 to 48 hours. Once you've provided all necessary documentation, such as your proof of address and income, the final verification is typically completed within one business day.
Is it better to get HP or PCP for a second-hand car?
The best choice depends on whether you value full ownership or lower monthly outgoings. Hire Purchase (HP) is usually the superior choice if you want to own the car outright at the end of the term and drive high annual mileages. Personal Contract Purchase (PCP) is often better if you prefer lower monthly costs and want the flexibility to change your vehicle every few years.
Can I settle my car finance agreement early?
Yes, you have a legal right to settle your finance agreement at any point under the Consumer Credit Act 1974. You can request a settlement figure from your lender, which includes the remaining principal balance minus a rebate for future interest. Lenders are permitted to charge a small fee for this early settlement, which is typically capped at approximately 58 days' worth of interest.
What happens if I exceed my mileage limit on a PCP deal?
Exceeding your agreed annual mileage will result in excess mileage charges if you choose to return the car at the end of the contract. In the 2026 market, these charges typically range from 3p to 30p for every additional mile covered. It's vital to be realistic about your driving habits at the start of the agreement to ensure you don't face an unexpected bill at the end.
Do I need a full UK driving licence to apply for car finance?
Yes, a full UK driving licence is generally a mandatory requirement for the majority of finance applications. It serves as a primary form of identification and confirms to the lender that you're legally permitted to drive the vehicle you are funding. If you only have a provisional licence, you'll likely find it much harder to secure used cars with finance without a guarantor.
Is the car mine as soon as I sign the finance agreement?
No, the finance company remains the legal owner of the vehicle until the final payment is made. You're the "registered keeper" on the V5C logbook, which means you're responsible for the insurance, tax, and maintenance of the car. Full legal ownership only transfers to you once the final instalment in an HP agreement or the optional balloon payment in a PCP deal is fully settled.


